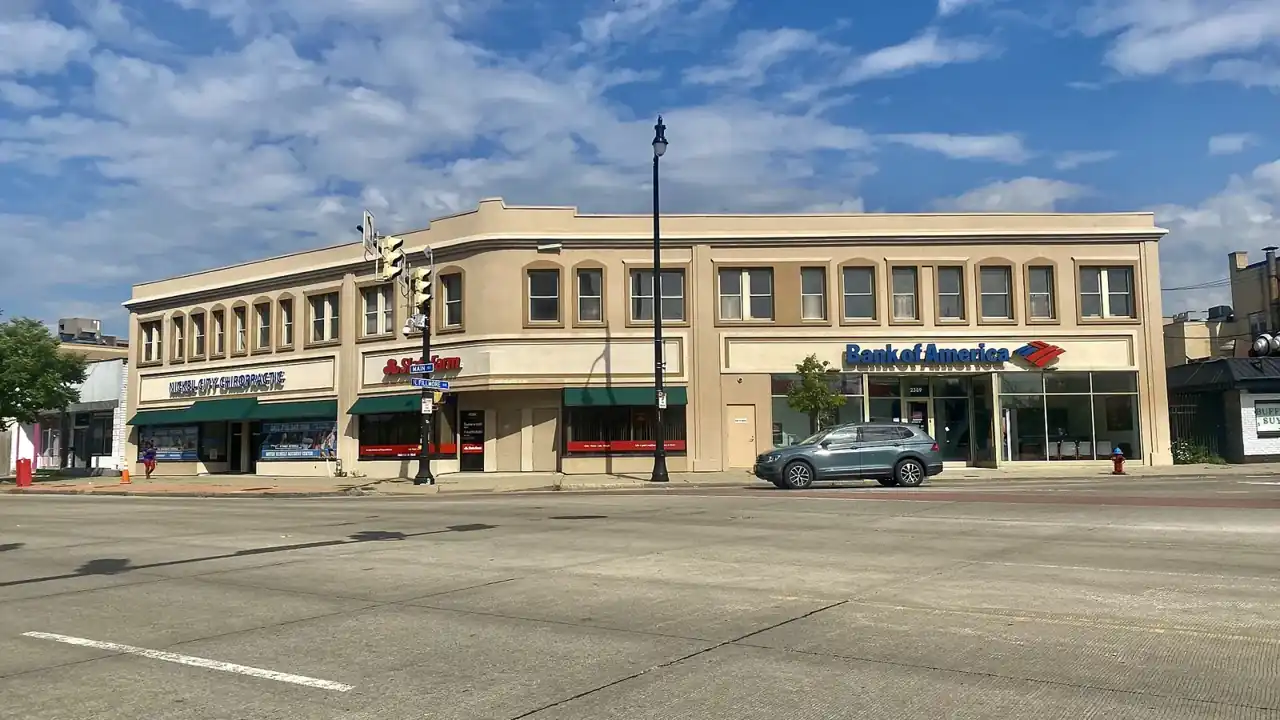
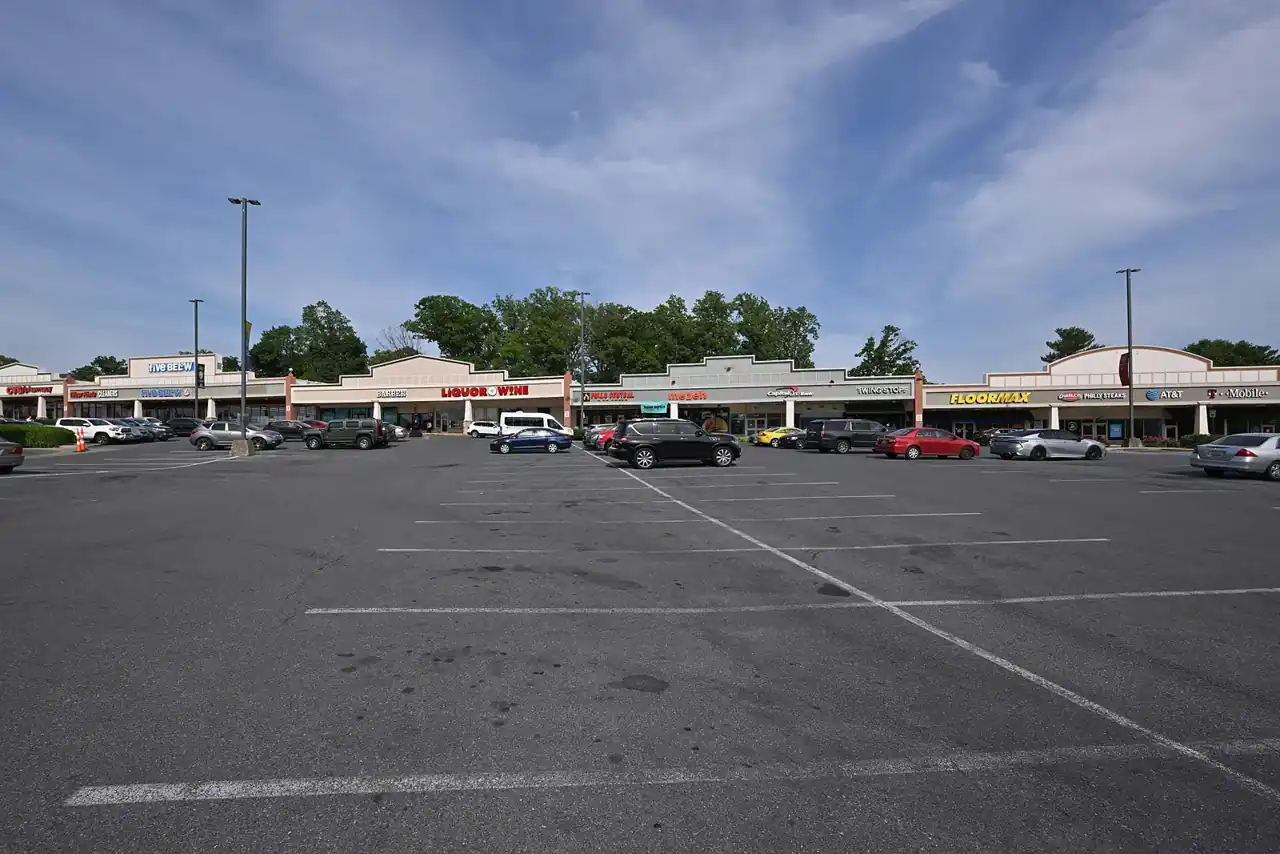
Retail properties range from a single storefront to a multi-tenant neighborhood center. Underwriting depends heavily on the tenants: who they are, how long their leases run, and how well the location serves them. A center anchored by service, food, and daily-needs tenants is viewed differently from one with significant vacancy or short remaining lease terms.
I review each retail scenario personally and then with one of NEXA Lending's in-house commercial lenders. NEXA Lending provides access to a large network of commercial lenders, so a property with a strong tenant base and one in transition can each be matched with an appropriate source of capital.
Common uses
- Purchase of a multi-tenant strip or neighborhood center
- Single-tenant or net-lease building acquisition
- Refinance or cash-out
- Repositioning a center with vacancy (often via bridge financing)
- Owner-user retail where your business occupies the space
What lenders typically review
- Rent roll, lease expirations, and tenant mix
- Tenant credit and length of operating history
- Traffic, visibility, access, and parking
- Operating expenses and reimbursement structure
- Vacancy and the plan to lease it
How I work your retail request
Here's how I work on every request. You send the basics: property or business, location, amount, and purpose. I personally review the scenario and ask whatever follow-up questions are needed to understand it properly. Then I review it with one of NEXA Lending's in-house commercial lenders, and together we look at realistic options. NEXA Lending provides access to a large network of commercial lenders, so the search isn't limited to a single bank's appetite.
You'll get a straight answer on what looks workable and what doesn't. If we move forward, I stay involved and work with the in-house lender and with you through closing. There is no cost or obligation to submit a scenario, and nothing on this page is an offer or a commitment to lend. Pricing and terms depend on the property, the borrower, and the market at the time.
Questions about retail financing
Can I finance a center that is partly vacant?
Often yes, though the structure may differ. A bridge loan can provide time to lease space before moving to longer-term financing.
I own the business that occupies the building. Does that change things?
Owner-occupied retail may qualify for SBA 504 or 7(a) programs or conventional owner-user loans. See the SBA loans page or send me the details.
Nationwide lending, local office
We finance commercial deals nationwide, in states where NEXA Lending can legally fund. My office is in Kirkland, Washington, and I also work closely with borrowers across Washington, including Bellevue, Spokane, Everett, Vancouver, WA, Tri-Cities. Send the details and I'll confirm how your state and property fit.
Submit your deal
Send the basics and I'll review them personally. No cost or obligation.